If you’ve toured a few model homes lately, you’ve probably seen the signs: “$15,000 in Free Upgrades!” or “Builder Paying Closing Costs!” Sounds great, right? So why do so many buyers still miss out on these offers?
Incentive examples in this article are illustrations, not current offers. Promotions, eligibility and lender terms can change. Confirm written terms and their effective date before relying on an offer. Any financing quote should state the date it was current.

Here’s the truth: builder incentives are real—but they’re also tricky. And if you don’t know what to look for (or what questions to ask), you could easily leave thousands on the table.
1. Incentives Are Often Tied to the Builder’s Preferred Lender
Some incentive packages require a specific lender or title company. Check the written offer rather than assuming the same conditions apply to every builder.
That can be a good deal if the rate and fees make sense—but sometimes, their “$10,000 in savings” disappears when you look closely at the loan terms.
An experienced agent can help you compare both options side-by-side so you know what’s truly best for your situation.
2. Incentives Change Every Month
Builders adjust their promotions based on sales goals and inventory.
For example, one week they might offer a free appliance package, and the next week it’s $20,000 toward design center upgrades.
If you’re not actively checking, you won’t even know what’s available—and that’s exactly how buyers miss the best deals.
That’s where having an agent who’s in and out of these communities weekly makes all the difference.
3. Incentives Often Come with “Strings”
That gorgeous kitchen upgrade credit? It might only apply to specific lots or spec homes.
Builders use incentives to move certain homes faster, so flexibility is key.
If you’re open to slightly adjusting your move-in date or lot preference, you may have more options, but ask which incentives can actually be combined.
4. Understand Your Representation Agreement
Your representation agreement should explain the services you will receive and how your broker will be paid. Compensation is negotiable. Before your first model-home visit, we should discuss those terms and confirm whether a builder is offering payment toward your broker’s compensation. Do not assume every builder or purchase has the same arrangement.
5. You Need to Ask the Right Questions
Here are a few you can start with:
- “Are there any current or upcoming incentives for this community?”
- “Do the incentives differ between inventory homes and to-be-built homes?”
- “Is this offer tied to your preferred lender or can I use my own?”
These questions open the door for real savings—and signal to the builder that you’re an informed buyer.
Compare the Full Cost Before Choosing an Offer
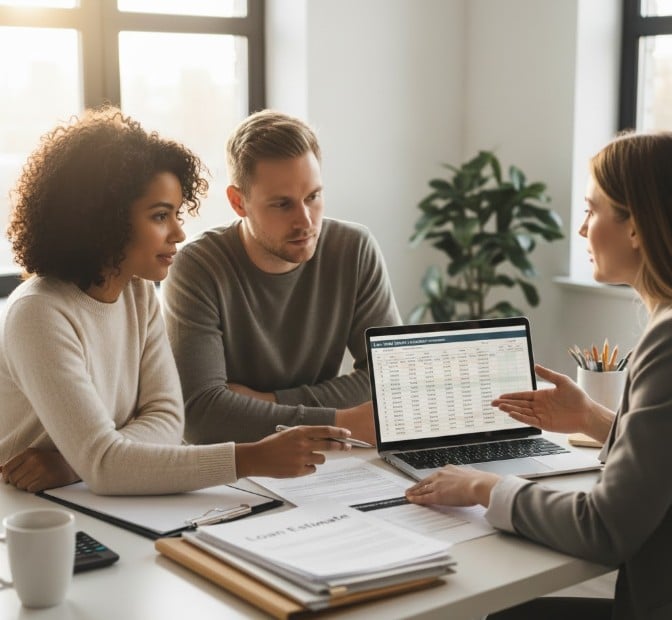
Compare the interest rate, points, lender fees, credits, cash to close and the payment after any temporary buydown ends. Ask for matching loan scenarios and review the Loan Estimates side by side. The largest advertised credit does not automatically produce the best overall terms.
Before touring, review five new-construction buying mistakes and the costs beyond the purchase price. For representation requirements, see TREC’s buyer-representation guidance.
Builder incentives can be a fantastic opportunity—but only if you know how to play the game.
That’s where I come in. I tour new communities across Celina, Prosper, and Frisco every week and keep track of current builder offers, so we can check what is available for the homes you are considering.

Thinking about buying new?
Contact Matt to compare communities and current written offers before you decide.
Let’s make sure you’re the one getting the deal this time.